Gold's role in a defensive Singapore portfolio
A practical view on how physical bullion sits alongside cash, SGS bonds, and equities in a Singapore-dollar-denominated portfolio — and where the friction points are.
Big Deal
Big Deal atelier
Gold is not an income asset. It pays no coupon, no dividend, no rent. For a Singapore saver whose default assets are CPF, SGS bonds, and a diversified equity portfolio, that fact does more work than any other in setting the correct allocation.
The right frame is not 'gold versus stocks' but 'what does gold do that the other holdings do not.' Three answers show up consistently across long data sets.
One: it uncouples from local rates
SGD-denominated cash and SGS bonds are, mechanically, exposed to MAS policy and to Singapore inflation. Gold, priced in USD but freely convertible, sits outside that policy loop. In periods where the SGD appreciates against the USD, dollar-priced gold underperforms in SGD terms; when the SGD softens, the reverse holds. This is a feature, not a bug — the asset is doing exactly the job it is being held for.
Two: it holds custody outside the banking system
A physical bar in a home safe or a bonded vault is not a claim on a counterparty. It is not exposed to the solvency of a broker, the operational status of an exchange, or the availability of a settlement rail. For a portfolio otherwise held entirely in book-entry form, this is a meaningful hedge against operational, not just market, risk.
Three: it is liquid at a distance
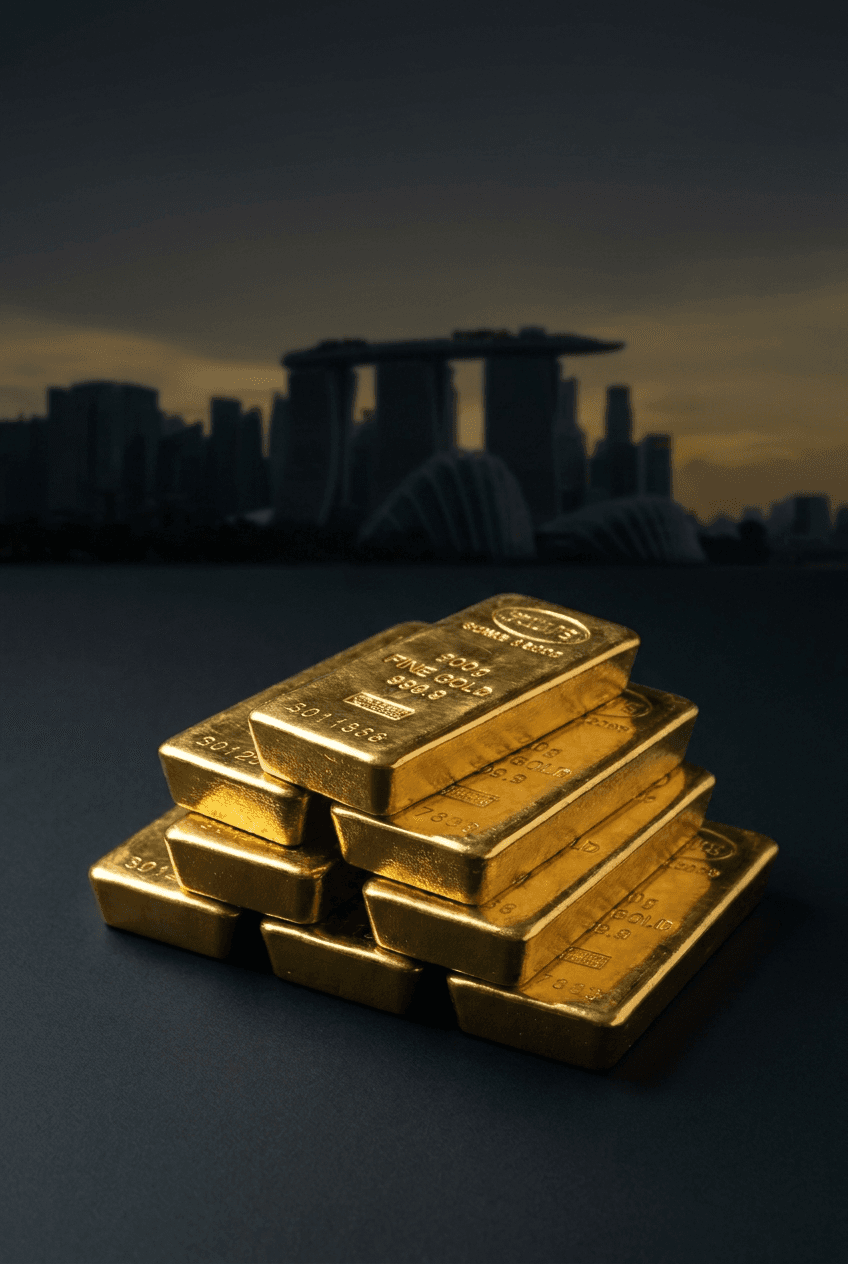
A 999.9 fine bar with a recognized serial and an intact assay card is transactable globally. That optionality has a value that does not show up in an expected-return calculation but does show up the moment a household needs to move value across a border.
Where the friction sits
The costs of physical bullion are real: dealer spread, storage, insurance, and the opportunity cost of holding a non-yielding asset. For a Singapore holder, IPM status removes the tax drag, and a properly negotiated vault contract keeps storage well under fifty basis points a year. What remains is the spread, and here the rule is simple: a serialized, hallmarked, LBMA-referenced bar from a house that will buy it back is worth more than a nominally identical piece of metal without those attributes.
None of this argues for a particular allocation. Sensible ranges vary from 5% to 15% of investable assets depending on the household's other holdings and its tolerance for a defensive drag. The point is only that the case for gold in a Singapore portfolio is not a case about return — it is a case about what happens when the rest of the portfolio behaves badly at the same time.
KEEP READING
More from the atelier
Policy
22 July 2026 · 6 min read
How Singapore's IPM tax exemption anchors the region's bullion demand
Since October 2012, Investment Precious Metals have been exempt from GST in Singapore — the quiet policy lever that turned the city into an Asian bullion hub.
Craft
8 July 2026 · 8 min read
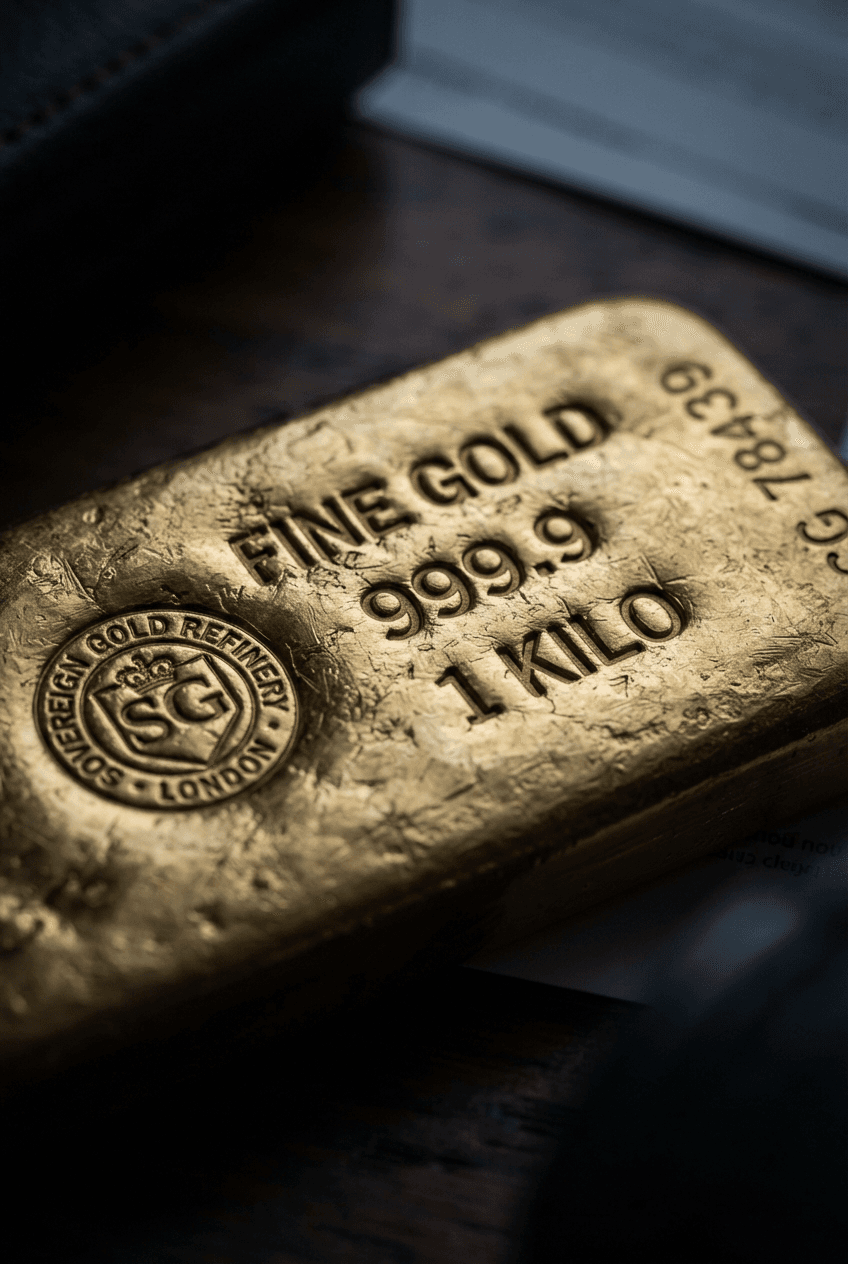
Reading the assay: what 999.9 really guarantees
Four nines fine is a chemistry claim, an audit claim, and a chain-of-custody claim — and each one is proven differently. A walk through what an assay card actually attests to.
Infrastructure
30 May 2026 · 5 min read
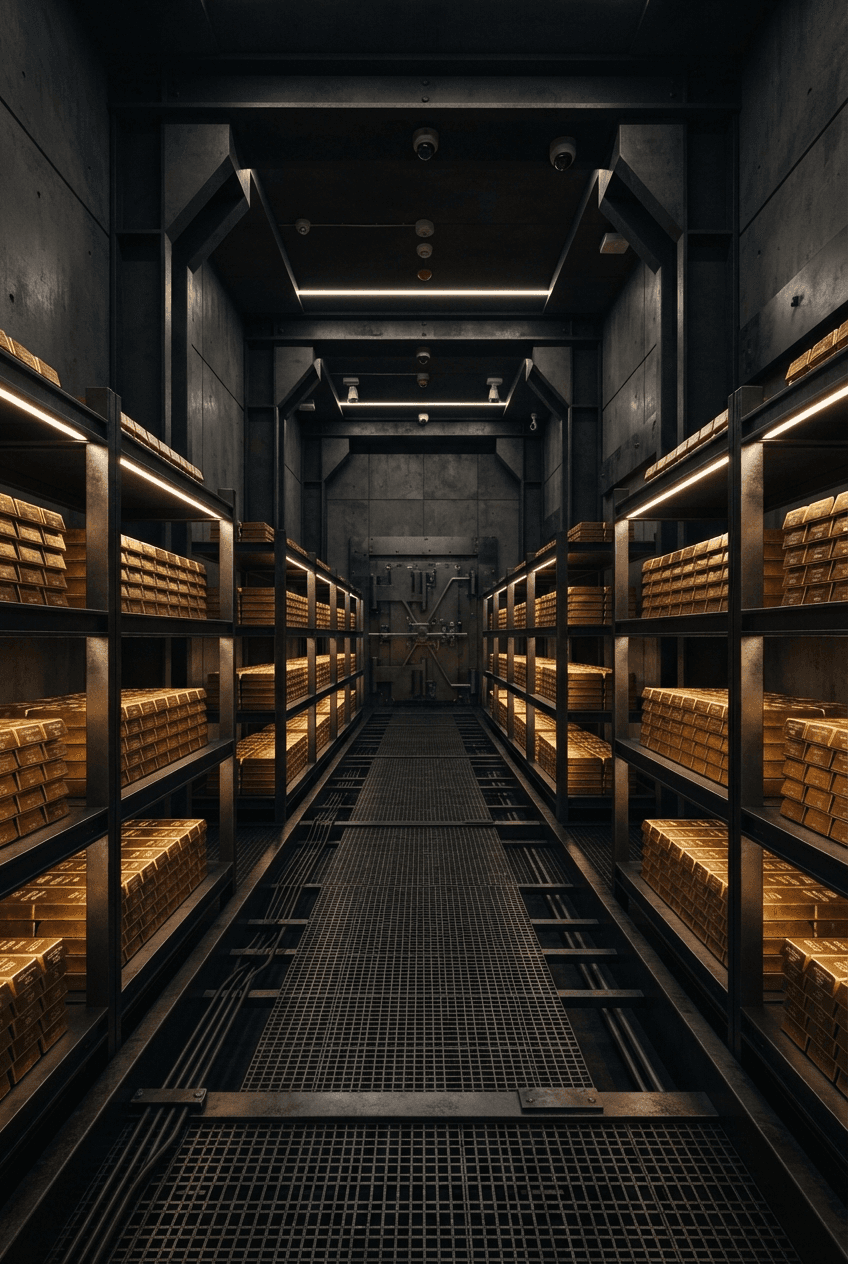
The vault economy: why physical gold sits in Singapore
The Singapore FreePort, bonded warehouse rules, and a jurisdictional read on property rights explain why an increasing share of Asian bullion is stored here rather than shipped through.